Pricing Products for Profit: A Practical Guide
Learn how to set prices that cover costs, attract customers, and drive sustainable profit for your small business.
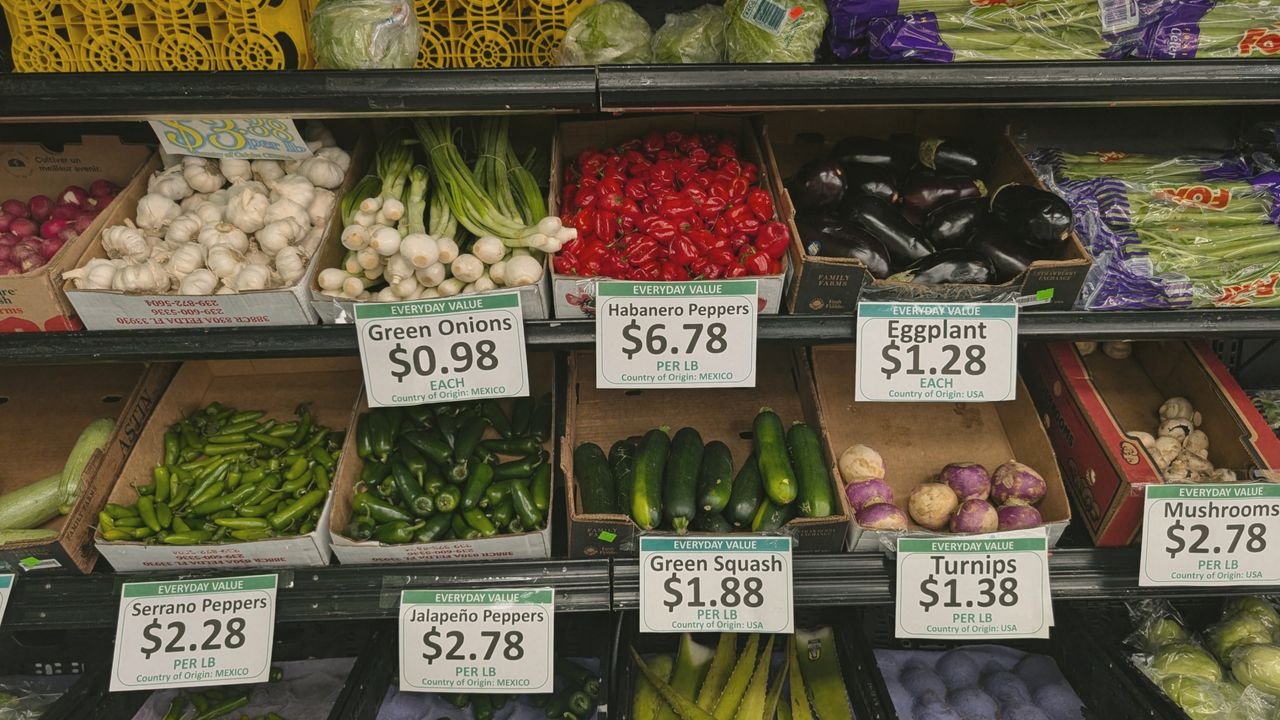
Photo: solle / Pexels
Start with a Clear Cost Foundation
Before you even think about the price tag, you need a solid understanding of what it costs to bring a product to market. List all direct costs—materials, labor, shipping, and any other expenses that change with each unit produced. Then add a fair share of indirect costs: rent, utilities, marketing, and general administration. The sum of these gives you a baseline that every price must exceed to stay profitable.
Know Your Customer and Market Position
A product’s price reflects more than cost; it signals value. Consider who buys your product and why. If your offering solves a critical problem, customers may be willing to pay a premium. If it’s a convenience item, price sensitivity will be higher. Positioning against competitors also matters: a boutique maker can price higher than a mass‑produced equivalent, while a budget retailer must stay close to the market average.
Gather this information through simple customer interviews, observation, and reviewing competitor listings. This insight helps you decide whether to price on cost, on value, or somewhere in between.
Choose a Pricing Strategy
Three common approaches can guide your decision: cost‑plus, value‑based, and competitive. Cost‑plus adds a markup to the cost base; it’s straightforward but may ignore customer perception. Value‑based sets price according to the benefit customers receive; it can capture more profit when the product truly differentiates. Competitive pricing aligns closely with rivals, useful in highly commoditized markets.
Often, a hybrid works best. For instance, a regional retailer might use cost‑plus for staples, but value‑based for specialty items that solve unique problems for local customers.
Test and Adjust
Pricing isn’t a one‑time decision. Start with a launch price, then monitor sales volume, customer feedback, and profit margins. If sales lag, consider a small discount or bundling. If demand is strong, a modest price increase can boost revenue without hurting volume. Use these adjustments as learning opportunities rather than arbitrary changes.
Maintain flexibility by setting price points that allow you to shift without confusing customers. For example, offer a standard price and a limited‑time discount that is clearly marked as temporary.
Protect Your Bottom Line
Once you settle on a price, protect it by monitoring costs. If material costs rise, revisit your markup or find suppliers with better terms. Keep an eye on overhead; a sudden increase in rent or utilities can erode margins if you don’t adjust prices accordingly.
Also, guard against price wars. If competitors drop prices, respond only if it aligns with your business goals. Maintaining a consistent price strategy builds trust and signals stability to customers.
Wrap‑Up
Pricing for profit is a blend of art and science. Start with accurate cost data, understand your market, choose a strategy that fits your product, test diligently, and stay vigilant about changes in cost and competition. By following these steps, small businesses can set prices that cover expenses, appeal to buyers, and sustain long‑term profitability.
This article was written with AI assistance. It offers general information, not personal financial, legal or career advice.